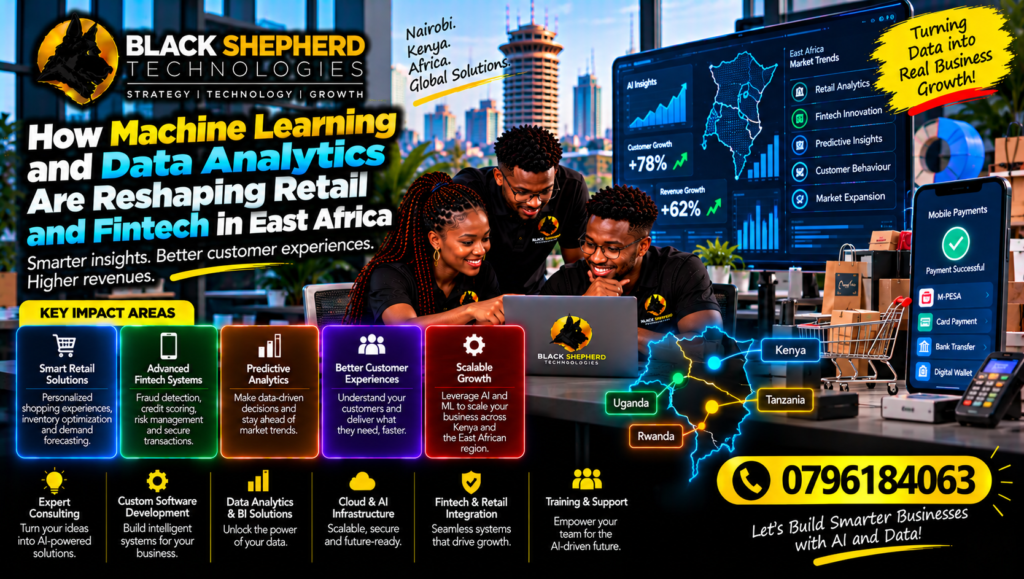
The economic landscape of East Africa—anchored by the thriving technological hubs of Nairobi, Kampala, Kigali, and Dar es Salaam—is undergoing a profound digital transformation. Over the past two decades, the region built a global reputation as a pioneer in mobile financial inclusion, largely driven by the explosive adoption of Safaricom’s M-Pesa and regional mobile money ecosystems. Today, East Africa stands at the beginning of an even more consequential technological evolution.
The convergence of machine learning (ML), big data analytics, and real-time cloud infrastructure is redefining how goods are sold and how capital flows across the region. Retailers, e-commerce platforms, micro-lenders, commercial banks, and logistics networks are moving away from traditional, reactive decision-making. Instead, forward-thinking enterprises are building intelligent, data-driven engines capable of predicting consumer demand, scoring credit risk in real time, personalizing digital storefronts, and optimizing complex supply chains.
For business executives, founders, and technology leaders across Kenya and East Africa, understanding this technological shift is no longer optional. It represents the primary frontier of competitive advantage. Companies that leverage machine learning and data analytics to eliminate operational friction and deliver hyper-personalized customer experiences are capturing dominant market share. Conversely, organizations relying on manual spreadsheets, static pricing models, and legacy risk frameworks face shrinking margins and customer attrition.
At Black Shepherd Technologies, we design and engineer high-performance software, custom web applications, and intelligent data automation platforms tailored specifically for the East African economic environment. If you are scaling your enterprise digital infrastructure or looking to build custom machine learning solutions, explore our professional engineering portfolio and projects to see how we bring market-leading technology solutions to life.
In this exhaustive 3,000-word strategic guide, we will analyze how machine learning and data analytics are reshaping the retail and fintech sectors in East Africa, covering predictive credit scoring, personalized e-commerce, algorithmic supply chain management, fraud prevention, and actionable strategies for enterprise implementation.
1. The East African Data Landscape: From Connectivity to Intelligence
To understand how machine learning is revolutionizing regional trade and finance, we must first examine the unique structural characteristics of East Africa’s digital ecosystem.
                  THE EAST AFRICAN DIGITAL DATA FLYWHEEL

 [ Ubiquitous Mobile Money ]  --->  [ Rich Granular Transaction Data ]
             ^                                     |
             |                                     v
 [ Instant Automated Execution ] <--- [ Machine Learning Models ]
The Abundance of Transactional Velocity
East Africa possesses one of the most active mobile money and digital transaction ecosystems in the world. Consumers and businesses across Kenya, Uganda, Tanzania, and Rwanda routinely perform daily micro-transactions—paying for groceries, settling utility bills, transferring peer-to-peer funds, and taking micro-loans—via USSD, smartphone applications, and mobile money rails.
This ubiquitous digital velocity creates a rich, continuous stream of high-frequency transactional data. Unlike Western markets where consumer credit histories are tracked primarily by centralized credit bureaus using traditional credit card and mortgage records, East Africa’s economic activity is captured through mobile money ledgers, telecommunication metadata, utility payment histories, and conversational trade logs.
The Shift from Data Collection to Predictive Intelligence
For years, local enterprises accumulated massive amounts of transactional data in siloed databases without extracting actionable commercial intelligence. Data was stored for basic accounting, manual audits, or basic monthly reporting.
Machine learning changes this equation fundamentally:
-
Descriptive Analytics: Tells you what happened in your business (e.g., “We sold 500 units of maize flour in Kisumu last month”).
-
Predictive Analytics: Tells you what will happen based on historical patterns (e.g., “Demand for maize flour in Kisumu will spike by 35% next Tuesday due to upcoming local market days and payroll cycles”).
-
Prescriptive Analytics: Tells you the optimal action to take automatically (e.g., “Automatically dispatch two additional trucks to the Kisumu distribution hub on Sunday and adjust local promotional pricing by 3% to maximize gross margins”).
Whether your organization operates in financial services, fast-moving consumer goods (FMCG), retail e-commerce, or specialized logistics, aligning your data infrastructure with modern algorithmic capabilities is essential. Explore our specialized industries we serve page to see how we build custom software platforms tailored to diverse commercial sectors.
2. Reshaping Fintech: Machine Learning in East African Financial Services
The East African financial technology sector has evolved far beyond basic peer-to-peer mobile money transfers. Today, machine learning algorithms form the core operational engine of modern credit scoring, automated underwriting, fraud detection, and digital wealth management platforms.
                    ML-DRIVEN FINTECH CREDIT PIPELINE

 [ Multi-Source Data Ingestion ] ---> [ Real-Time Feature Engineering ]
 (Mobile money, SMS, App logs)       (Cash flow velocity, repayment history)
                                                |
                                                v
 [ Automated Disbursal / Decline ] <--- [ ML Risk Scoring Model ]
 (Under 60-second execution)         (XGBoost / Random Forest Classification)
1. Alternative Credit Scoring and Automated Underwriting
Traditional commercial banking models required borrowers to present formal pay slips, physical collateral, land title deeds, or years of audited financial statements. This structural requirement historically excluded millions of informal traders, micro-entrepreneurs, and small-to-medium enterprises (SMEs) across East Africa.
Machine learning models have bridged this financial gap by developing sophisticated alternative credit scoring frameworks:
-
Behavioral Feature Engineering: ML algorithms analyze non-traditional data points—including mobile money turnover velocity, airtime top-up frequency, utility bill payment consistency, geographic stability, and peer-network reliability.
-
Instant Risk Classification: Gradient boosting algorithms (such as XGBoost) and neural networks evaluate hundreds of risk variables simultaneously, assigning a precise credit limit and risk-adjusted interest rate in under 30 seconds.
-
Dynamic Credit Limit Scaling: As borrowers accept small micro-loans and repay them consistently, machine learning models continuously recalibrate credit limits upwards in real time, fostering responsible credit expansion without increasing non-performing loan (NPL) ratios.
2. Algorithmic Fraud Detection and Risk Mitigation
As digital transaction volumes surge across East Africa, financial institutions face sophisticated cyber threats—including SIM-swap fraud, account takeover attacks, identity theft, and synthetic credit default rings.
Traditional, static rule-based fraud detection systems (e.g., “Flag any transfer over KES 100,000”) are no longer sufficient. They generate high rates of false positives—blocking legitimate customer transactions—while missing complex, multi-step fraud patterns.
Modern machine learning platforms utilize anomaly detection algorithms to protect financial networks:
-
Real-Time Behavioral Profiling: Machine learning models establish baseline behavioral profiles for every account user—tracking typical device fingerprints, login locations, transaction times, velocity, and recipient networks.
-
Instant Anomaly Scoring: When a user initiates a transaction that deviates significantly from their historical pattern (e.g., a sudden late-night login from an unfamiliar IP address attempting multiple rapid transfers), the ML engine flags or temporarily halts the transaction for multi-factor authentication before funds leave the ecosystem.
-
Graph Neural Networks (GNNs): Advanced fintech platforms deploy graph analytics to uncover hidden syndicate networks—identifying clusters of accounts sharing subtle hardware identifiers or rotating funds to simulate fake business activity.
3. Hyper-Personalized Digital Banking and Wealthtech
Machine learning is transforming generic banking applications into intelligent personal financial management advisers:
-
Predictive Cash-Flow Management: ML algorithms analyze a micro-business owner’s income and expense cycles, predicting upcoming liquidity shortfalls and offering proactive working capital buffers before inventory runs out.
-
Automated Micro-Savings and Investments: Wealthtech applications analyze daily spending habits, automatically rounding up digital transactions and sweeping spare change into interest-bearing money market funds (MMFs) or localized digital asset pools.
-
Reshaping Retail: Data Analytics and ML in East African Commerce
While fintech pioneered early machine learning adoption in the region, the retail sector—spanning physical supermarket chains, informal FMCG distribution networks, and digital e-commerce platforms—is experiencing a parallel data revolution.
                     RETAIL DATA ANALYTICS MATRIX

  RETAIL PILLAR             TRADITIONAL APPROACH              ML & ANALYTICS APPROACH
  ------------------------  --------------------------------  ------------------------------------
  Demand Forecasting        Manual guesswork & gut feel       Predictive ML models based on data
  Inventory Management      Static safety stock buffers       Dynamic, automated stock replenishment
  Customer Experience       Generic broadcast discounts       Hyper-personalized recommendations
  Price Optimization        Fixed, rigid price tags           Dynamic pricing based on local demand
1. Predictive Demand Forecasting and Inventory Optimization
Managing retail inventory across East Africa presents complex operational challenges. Importers, wholesalers, and retail chains must manage long import lead times, fluctuating port clearance schedules, currency exchange volatility, and regional transport bottlenecks.
Under-stocking results in immediate lost revenue and customer defection, while over-stocking ties up valuable working capital and increases perishable shrinkage.
Machine learning models solve this puzzle through advanced time-series forecasting:
-
Multi-Variable Input Analysis: ML models analyze historical sales records alongside external environmental variables—including local rainfall patterns, public holidays (such as Eid, Christmas, or Back-to-School seasons), agricultural harvest timelines, and inflation indices.
-
Localized Stock Allocation: Instead of treating all retail branches uniformly, predictive models calculate exact inventory requirements per individual store or distribution hub. A supermarket branch in Kilimani, Nairobi receives a completely different inventory allocation mix than a branch in Eldoret or Malindi based on hyper-local purchasing behaviors.
-
Automated Purchase Orders: Modern retail ERPs connected to machine learning engines automatically generate and dispatch purchase orders to local suppliers when stock levels reach mathematically optimized reorder points, eliminating human lag and stockout risks.
2. Conversational Commerce and Personalized E-Commerce UX
In East Africa, e-commerce does not exist purely on desktop web pages. Digital trade is overwhelmingly mobile-first and deeply conversational—taking place across WhatsApp Business, Instagram, and lightweight mobile web interfaces.
Machine learning elevates conversational commerce into a high-converting automated sales channel:
-
Personalized Recommendation Engines: When a customer browses an online store or chats with a shopping bot, collaborative filtering and natural language processing (NLP) models analyze their past purchases, search queries, and browsing duration to recommend complementary products (e.g., “Customers who bought this smartphone also purchased this protective case and screen protector”).
-
Automated WhatsApp AI Sales Agents: Generative AI models fine-tuned on company product catalogs converse fluently in English, Swahili, and local Sheng. They answer technical product specifications, verify stock availability, and trigger instant M-Pesa STK push payment prompts directly inside the chat interface.
3. Digitizing the Informal Retail Sector (Sokos and Duka Networks)
Over 80% of retail trade in East Africa takes place through informal commercial channels—neighborhood dukas, open-air markets, kiosks, and small family-run shops. Modern tech platforms are deploying machine learning and data analytics to digitize this massive informal distribution layer.
B2B e-commerce platforms connect informal shopkeepers directly to FMCG manufacturers:
-
Aggregated Purchasing Power: Data analytics aggregates ordering patterns across thousands of small dukas, allowing manufacturers to optimize delivery routes and offer wholesale pricing to informal retailers.
-
Embedded Merchant Credit: Machine learning engines evaluate an informal shopkeeper’s daily inventory ordering history through the B2B app, extending short-term stock financing (Buy Now, Pay Later for inventory) so the merchant can keep their shelves fully stocked without upfront cash constraints.
-
Architectural Blueprint: Building Machine Learning & Analytics Infrastructure
For executive leadership, understanding the commercial value of machine learning is only the first step. The critical question becomes: How do we build and deploy a modern, scalable data architecture within our business?
Deploying production-grade machine learning models requires a structured, multi-tier data pipeline that ensures data accuracy, security, and low-latency execution.
               ENTERPRISE DATA & MACHINE LEARNING ARCHITECTURE

 [ DATA SOURCES ]          [ DATA PIPELINE ]          [ ANALYTICS & ML CORE ]     [ CONSUMPTION LAYER ]
 - Mobile Money APIs   ->  - Ingestion (Kafka)   ->  - Feature Store         ->  - Real-Time Risk APIs
 - E-Commerce DBs          - Data Lake (S3/GCS)      - ML Training (XGBoost)     - Executive Dashboards
 - Web/App Analytics       - Data Warehouse          - Inference Engine          - Automated STK Push
Tier 1: Unified Data Ingestion and ETL Pipelines
Machine learning models are only as good as the underlying data used to train them. If an enterprise’s data remains fragmented across disconnected software applications, unorganized spreadsheets, and raw payment receipts, building reliable predictive models is impossible.
-
Data Aggregation: Modern architectures deploy automated Extract, Transform, Load (ETL) pipelines that continuously pull data from transactional databases, mobile money webhooks, web analytics, CRM systems, and ERP platforms into a centralized repository.
-
Data Cleansing & Normalization: Raw data is cleaned, deduplicated, and formatted to ensure consistent data structures across all business units.
Tier 2: The Enterprise Data Warehouse / Data Lake
Once ingested, data must be stored in scalable, high-performance cloud environments optimized for analytics queries:
-
Cloud Storage: Utilizing enterprise cloud data warehouses (such as Google BigQuery, Snowflake, or Amazon Redshift) enables organizations to run complex analytical queries across millions of historical transaction records in seconds.
-
Role-Based Security: Data structures must incorporate strict access controls and anonymization protocols to ensure sensitive customer records remain fully protected.
Tier 3: Feature Engineering and Model Training
In this core analytical layer, data scientists and machine learning engineers transform raw variables into predictive features:
-
Model Selection: Depending on the commercial objective, teams train supervised learning algorithms (for credit scoring and churn prediction), unsupervised clustering models (for customer segmentation), or time-series models (for inventory forecasting).
-
Continuous Model Validation: Machine learning models are continuously tested against fresh incoming data to prevent “model drift”—ensuring that predictive accuracy remains high even as economic conditions or consumer habits change.
Tier 4: Real-Time API Inference and Operational Execution
The ultimate value of a machine learning model lies in its ability to execute real-time business decisions at the point of customer interaction:
-
Low-Latency APIs: Trained ML models are deployed as lightweight REST APIs. When a customer applies for a micro-loan on a mobile app or hits the checkout button on an e-commerce platform, the application sends a fast API call to the machine learning inference engine.
-
Sub-Second Execution: The model evaluates the request, calculates the risk score or recommendation, and returns an automated decision back to the user interface in milliseconds.
-
Overcoming Key Challenges: Data Privacy, Bias, and Infrastructure
While the potential of machine learning and data analytics in East Africa is vast, business leaders must navigate several critical operational, legal, and technical hurdles.
1. Data Protection Compliance and Regional Governance
With the active enforcement of the Kenya Data Protection Act, Uganda Data Protection and Privacy Act, and equivalent regional privacy frameworks, data governance has become a boardroom priority.
Enterprises collecting, processing, or training machine learning models on customer data must maintain strict compliance:
-
Explicit Customer Consent: Organizations must obtain clear, informed consent from users before collecting personal data for automated profiling or credit assessment.
-
Right to Explanation: Regulatory frameworks increasingly mandate that financial institutions provide customers with clear explanations if an automated machine learning algorithm declines a credit or service application.
-
Data Security & Encryption: Customer identifiers and financial records used in data analytics pipelines must be encrypted both in transit and at rest using enterprise-grade cryptographic standards.
2. Algorithmic Bias and Responsible AI
Machine learning models learn strictly from historical data. If historical lending practices or commercial dataset collections reflect underlying socio-economic biases, the machine learning model will perpetuate and amplify those biases.
-
Fairness Audits: Tech teams must conduct regular fairness and bias audits on credit scoring models to ensure algorithms do not systematically discriminate against specific demographic groups, geographic regions, or newer micro-entrepreneurs lacking lengthy historical records.
-
Human-in-the-Loop Oversight: For high-value transactions, complex credit applications, or sensitive customer complaints, enterprises must maintain a “human-in-the-loop” escalation framework, allowing human risk officers to review and override automated algorithmic decisions when necessary.
3. Managing Infrastructure Latency and Connectivity
While urban centers like Nairobi and Kigali boast high-speed 4G and growing 5G fiber-optic networks, upcountry regions often operate on fluctuating cellular connectivity.
-
Lightweight Architectures: Machine learning applications designed for field deployment must feature lightweight frontends and edge-computing capabilities that can queue data locally during offline states and synchronize seamlessly once network connectivity is restored.
-
Driving Sustainable Enterprise Growth with Advanced SEO
Building sophisticated machine learning architectures, predictive inventory models, and automated credit engines ensures that when customers interact with your business, they experience world-class speed, personalization, and reliability. However, internal operational excellence and advanced technology are only half of the commercial growth equation. Your enterprise must also capture continuous, high-intent market demand.
If prospective corporate clients, B2B buyers, or retail consumers searching for your products and services online cannot discover your digital platform on Google, your competitors will capture that market share. Implementing technical SEO, structured schema markup, fast page speed optimization, and targeted local content strategies is essential for dominating search engine results pages. Partnering with professionals providing expert SEO services in Kenya is the most sustainable way to drive high-value organic traffic directly to your digital ecosystem.
Conclusion: The Data-Driven Imperative for East African Business
The transformation of retail and fintech across East Africa is no longer a distant theoretical vision; it is an active, rapidly accelerating commercial reality. Machine learning and data analytics have shifted from novel competitive advantages into essential, foundational business infrastructure.
By transitioning from manual, reactive processes to intelligent, predictive data systems, enterprises across Kenya and East Africa can score credit risk in real time, eliminate inventory stockouts, automate customer support, prevent financial fraud, and deliver hyper-personalized digital experiences that build lasting customer loyalty.
Embracing this data-driven future requires strategic vision, robust software engineering, uncompromising data governance, and experienced technology partners.
At Black Shepherd Technologies, we empower corporate enterprises, fintech innovators, retail networks, and growing businesses across East Africa with elite custom software engineering, scalable cloud data pipelines, and intelligent machine learning solutions. Get in touch with our engineering team today to audit your current technology stack, unlock the power of your corporate data, and build a market-leading digital platform engineered for sustainable, scalable growth.